Know your budget
Look beyond the purchase price. Your down payment, closing costs and comfortable monthly payment all matter.
First-time homebuyers in Ontario
There is a lot to consider before you receive the keys. I’ll help you understand the numbers, compare your options and move forward one step at a time—without pressure—across Kawartha Lakes, Peterborough, Durham Region and the GTA.
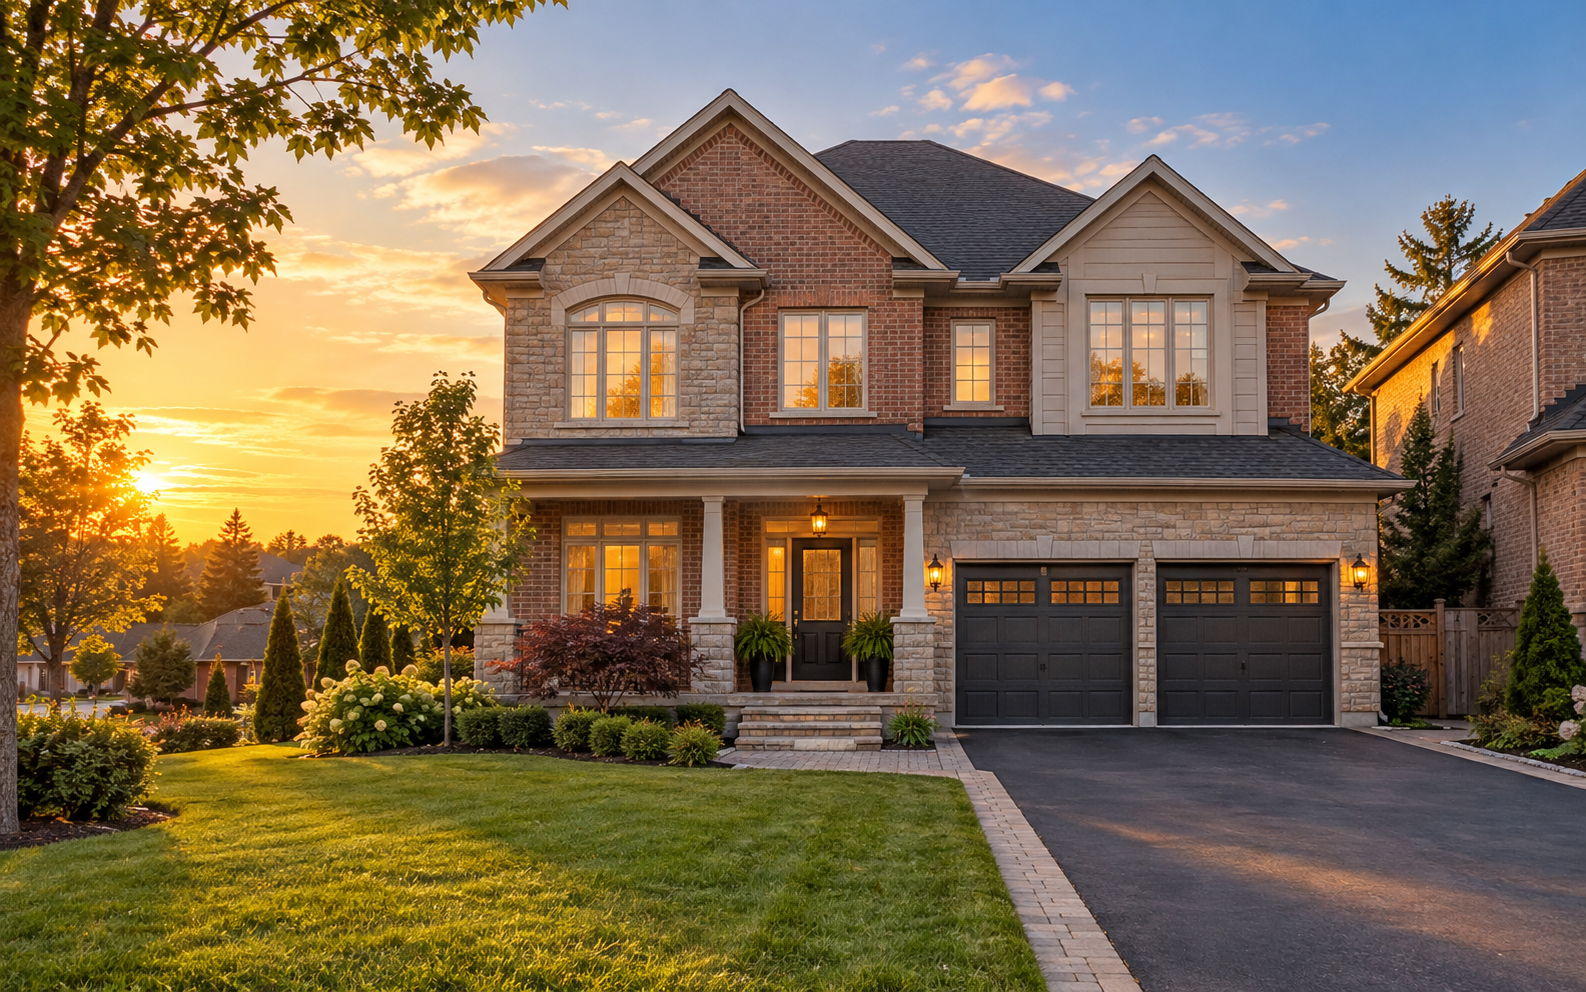
Look beyond the purchase price. Your down payment, closing costs and comfortable monthly payment all matter.
A mortgage preapproval helps you understand your price range and strengthens your position when it is time to offer.
We’ll look at value, condition, neighbourhood and future costs—not simply whether a home looks good at the showing.
You’ll understand the price, conditions and risks before signing, with time to ask questions along the way.
Plan for the full purchase
Before viewing homes seriously, it helps to understand the money needed before closing and the costs that continue after you move in.
Estimate your numbersFor an insured mortgage, the minimum is generally 5% on the first $500,000 and 10% on the portion above $500,000. Homes priced at $1.5 million or more generally require at least 20% down.
Ontario charges provincial land transfer tax. Toronto properties also have a separate municipal land transfer tax. Eligible first-time buyers may receive rebates that reduce these amounts.
With less than 20% down, mortgage-default insurance is normally required. The premium can usually be added to the mortgage, but Ontario tax on that premium is payable at closing.
Plan for legal fees, title insurance, registration costs, adjustments and possible inspection or appraisal costs. Exact amounts depend on the property and transaction.
Possible first-time-buyer savings
Eligibility rules apply. Outside Toronto, only the Ontario rebate applies. Your lawyer confirms qualification and the final tax payable.
The buying process
You do not need to know everything before you begin. You just need to know what comes next.
Review your available cash, monthly costs and future plans.
Compare financing options and understand the conditions behind the rate.
Separate the must-haves from features you can compromise on.
Look at condition, value and ownership costs with a critical eye.
Decide on price, deposit, conditions, closing date and negotiation strategy.
Work with your lender and lawyer to satisfy conditions and prepare for possession.
Let’s review your questions, budget and next steps.
Information is general and may change. Mortgage approval, rebates and tax treatment depend on individual eligibility and the property. Confirm financial matters with a lender or mortgage broker and legal or tax matters with the appropriate professional.